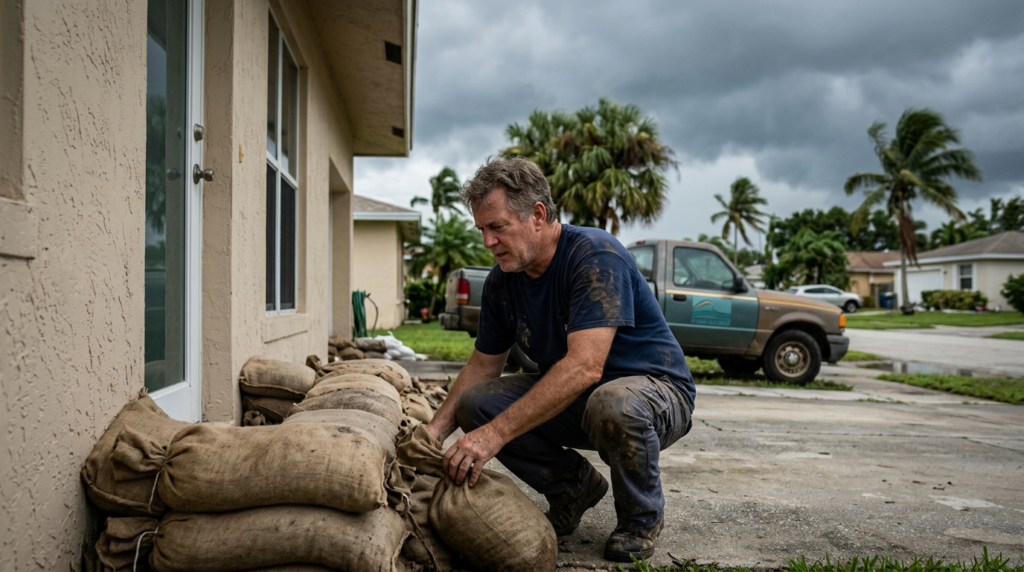
Flood insurance in Miami, FL typically costs between $800 and $4,000+ per year depending on your property’s flood zone designation, elevation, construction type, and coverage limits. Standard homeowners insurance does not cover flood damage, yet much of Miami-Dade County sits in FEMA-designated Special Flood Hazard Areas where flooding from hurricanes, tropical storms, king tides, and heavy rainfall is a regular threat — not a hypothetical one. If you own property in Miami, separate flood insurance isn’t optional; it’s essential.
At SOVA Insurance, we compare flood policies from the National Flood Insurance Program (NFIP) and private flood carriers to find the right balance of coverage and cost for your Miami property.
Why Every Miami Property Needs Flood Insurance
Miami is among the most flood-vulnerable cities in the United States. The combination of low-lying terrain, proximity to the Atlantic Ocean, aging stormwater infrastructure, and increasingly frequent king tide events means flood risk extends far beyond official FEMA flood zones.
Key facts Miami property owners should know:
- Homeowners insurance explicitly excludes flood damage — water that enters your home from outside is not covered under your HO-3 policy
- Nearly one-third of all NFIP flood claims nationwide come from outside high-risk flood zones
- Just one inch of water in an average home can cause more than $25,000 in damage
- Properties in FEMA-designated Special Flood Hazard Areas (zones AE, AH, VE) with federally-backed mortgages are required to carry flood insurance
- Miami-Dade County’s Community Rating System (CRS) Class 5 status provides significant premium discounts for NFIP policyholders
Even if your property is in Zone X (minimal flood risk), the reality in Miami is that afternoon thunderstorms can dump multiple inches of rain in less than an hour, overwhelming drainage systems and flooding streets and homes that have never flooded before.
Learn more about homeowners insurance in Miami.
NFIP vs. Private Flood Insurance: Which Is Right for You?
Miami property owners have two main options for flood coverage, and understanding the differences can save you thousands of dollars.
National Flood Insurance Program (NFIP)
The NFIP is the federal flood insurance program administered by FEMA and delivered through more than 47 private insurance companies in the Write-Your-Own (WYO) program.
NFIP coverage limits:
– Residential building coverage: Up to $250,000
– Residential contents coverage: Up to $100,000
– Commercial building coverage: Up to $500,000
– Commercial contents coverage: Up to $500,000
Key characteristics:
– Rates set by FEMA using Risk Rating 2.0, which prices policies based on individual property risk factors including flood frequency, distance to water, building elevation, and replacement cost
– 30-day waiting period before coverage takes effect (exceptions for new home purchases and map changes)
– Does not cover additional living expenses (ALE) if your home is uninhabitable
– Does not cover basement contents beyond essential service equipment (water heaters, furnaces, washers/dryers)
– Available to anyone in a participating NFIP community — all of Miami-Dade County participates
Private Flood Insurance
Florida has one of the most active private flood insurance markets in the country, with dozens of carriers writing standalone flood policies.
Advantages over NFIP:
– Higher coverage limits available — critical for Miami homes valued above $250,000 (which is most of them)
– Shorter waiting periods — some policies take effect in as little as 10–14 days
– Additional living expense (ALE) coverage — pays for temporary housing if your home is uninhabitable
– Replacement cost coverage options — NFIP pays actual cash value on contents, while some private carriers offer full replacement cost
– May be significantly cheaper for newer, elevated homes in moderate-risk zones
Considerations:
– Coverage breadth varies by carrier — some private policies have more exclusions than NFIP
– Florida law (Section 627.715, Florida Statutes) requires standard and preferred private flood policies to be “at least as broad” as NFIP coverage
– Private carriers can non-renew or withdraw from the Florida market, while NFIP guarantees renewal
– Not all mortgage lenders accept private flood insurance in lieu of NFIP (though most do under federal guidelines)
Which Should You Choose?
| Factor | NFIP | Private Flood |
|---|---|---|
| Max building coverage | $250,000 | $1M–$5M+ |
| Max contents coverage | $100,000 | $500K+ |
| Additional living expenses | Not covered | Often included |
| Waiting period | 30 days | 10–14 days (varies) |
| Pricing for high-risk zones | Competitive | May be higher |
| Pricing for low-risk/elevated homes | Often more expensive | Often cheaper |
| Guaranteed renewal | Yes | No |
Bottom line: For properties valued under $250,000 in high-risk flood zones, NFIP is often the better value. For higher-value homes, newer construction, or properties with favorable elevation certificates, private flood insurance frequently offers better coverage at competitive or lower rates. The smartest approach is to compare both — which is exactly what SOVA Insurance does for every client.
Miami-Dade CRS Discount: Your Built-In Savings
Unincorporated Miami-Dade County participates in FEMA’s Community Rating System (CRS) and holds a Class 5 rating — one of the best in the nation. This translates directly into lower NFIP premiums:
- 25% discount on flood insurance premiums for properties in Special Flood Hazard Areas (high-risk zones)
- 10% discount for properties in moderate-to-low risk zones (Zone X)
This discount is applied automatically to NFIP policies for properties in participating areas. It’s the result of Miami-Dade’s investments in stormwater management, drainage improvements, and floodplain regulations.
Important: CRS discounts apply only to NFIP policies, not private flood insurance. However, private carriers may offer their own competitive rates that offset this difference. Always compare both options.
How Much Does Flood Insurance Cost in Miami?
Flood insurance costs in Miami vary dramatically based on property-specific risk factors under FEMA’s Risk Rating 2.0 methodology:
- Low-risk properties (Zone X, elevated): $400–$1,200/year
- Moderate-risk properties: $800–$2,500/year
- High-risk properties (Zone AE near coast): $2,000–$6,000+/year
- High-value waterfront properties: $5,000–$15,000+/year
What Drives Your Flood Insurance Cost
- Flood zone designation: Properties in zones AE, AH, and VE (high-risk) pay significantly more than those in Zone X (moderate-to-low risk)
- Building elevation relative to Base Flood Elevation (BFE): Homes elevated above BFE pay substantially less. An elevation certificate can document this and reduce your premium
- Distance to water sources: Proximity to Biscayne Bay, the Miami River, canals, and the ocean increases risk and cost
- Building age and type: Homes built before FEMA flood maps were adopted (pre-FIRM) may qualify for subsidized rates, while newer construction with flood-resistant features gets better pricing
- Foundation type: Elevated homes on stilts or pilings pay less than slab-on-grade construction
- Coverage amount and deductible: Higher coverage limits and lower deductibles increase premiums
How to Lower Your Flood Insurance Premium
Get an elevation certificate. If your property sits above the base flood elevation, documenting this with a licensed surveyor can substantially reduce your NFIP premium — savings of 30–60% are not uncommon.
Request a LOMA (Letter of Map Amendment). If your property was incorrectly mapped into a high-risk flood zone, a professional land surveyor can survey your property and apply to FEMA for reclassification to Zone X. If approved, this can eliminate the mandatory purchase requirement and dramatically reduce your premium.
Compare NFIP and private carriers. Newer, elevated homes often get better rates from private flood insurers. SOVA Insurance quotes both options side by side so you can choose the best value.
Increase your deductible. Raising your flood insurance deductible from $1,000 to $5,000 or $10,000 can reduce your annual premium by 15–30%.
Take advantage of CRS discounts. Ensure your NFIP policy reflects the Miami-Dade CRS Class 5 discount — verify this appears on your declarations page.
Learn more about condo insurance in Hollywood, FL.
Why Miami Homeowners Choose SOVA Insurance for Flood Coverage
As an independent agency, SOVA Insurance is not locked into the NFIP or any single private carrier. We compare flood insurance options from the NFIP (through our WYO carrier relationships) and multiple private flood insurers to find the combination of coverage and price that works for your specific property.
What makes us different:
- Side-by-side comparison: We quote NFIP and private flood policies simultaneously so you can see exactly which option offers more coverage for less money
- Elevation certificate guidance: We’ll tell you whether obtaining an elevation certificate could save you money and connect you with licensed surveyors in Miami-Dade
- LOMA expertise: If your property may qualify for a map amendment, we guide you through the process
- Multilingual service: Our team speaks English, Russian, and Ukrainian, making flood insurance accessible for Miami’s diverse homeowner community
- Claims support: When floodwaters recede, we help you navigate the claims process — from documentation requirements to proof-of-loss deadlines — so you get the maximum payout you’re entitled to
Frequently Asked Questions
Is flood insurance required in Miami?
Flood insurance is legally required if your property is in a FEMA-designated Special Flood Hazard Area and you have a federally-backed mortgage. Even outside high-risk zones, some lenders independently require flood insurance as a loan condition. Given that nearly one-third of all NFIP flood claims come from outside high-risk areas, flood insurance is strongly recommended for every Miami property owner regardless of zone designation.
How much does flood insurance cost in Miami?
Costs range from approximately $400 per year for low-risk properties in Zone X to $6,000+ for high-risk properties near the coast. The average Miami homeowner in a moderate-risk zone pays roughly $1,200–$2,500 annually for NFIP coverage. Private flood insurance may be significantly cheaper for newer, elevated homes. An elevation certificate can reduce NFIP premiums by 30–60% if your home is above the base flood elevation.
What’s the difference between flood insurance and homeowners insurance?
Homeowners insurance covers damage from internal water events (burst pipes, appliance leaks) and wind damage from storms, but it explicitly excludes flood damage — defined as water entering your home from an external source such as rising rivers, storm surge, heavy rainfall runoff, or overwhelmed drainage systems. Flood insurance is a completely separate policy purchased through the NFIP or a private carrier. In Miami, you need both policies for full protection.
Does the NFIP cover my condo in Miami?
Yes. Condo unit owners can purchase NFIP flood insurance for their unit’s contents (up to $100,000) and for building improvements they’ve made to the unit. The condo association should carry a separate flood policy for the building structure. SOVA Insurance can help both condo owners and associations find appropriate flood coverage.
How long does it take for flood insurance to take effect?
NFIP policies have a standard 30-day waiting period from purchase to effective date. Exceptions apply if you’re purchasing flood insurance as part of a new home closing or due to a flood map change. Many private flood carriers offer shorter waiting periods of 10–14 days. This is why buying flood insurance before hurricane season begins on June 1 is critical — waiting until a storm is approaching means you won’t be covered.
Get Flood Insurance in Miami — Free Quote Today
Don’t wait for the next king tide or hurricane to find out your homeowners insurance won’t cover the damage. SOVA Insurance compares NFIP and private flood policies side by side to find you the best coverage at the lowest price for your Miami property. Whether you own a single-family home in Coconut Grove, a condo in Brickell, or a rental property in Doral, we’ll make sure you’re protected. Call us today or request a free online flood insurance quote.