Sova Insurance
(954) 758-5111 Get a Quote →
🔧 Contractor Insurance · Florida

Insurance for Florida contractors — GL, workers comp, truck and bond in one place

General liability, workers comp, commercial auto, tools and bonds — written by one licensed Florida agency. Free quote, no obligation.
  • ✓Licensed Florida agents
  • ✓500+ clients
  • ✓5.0 Google rating
  • ✓Hollywood, FL
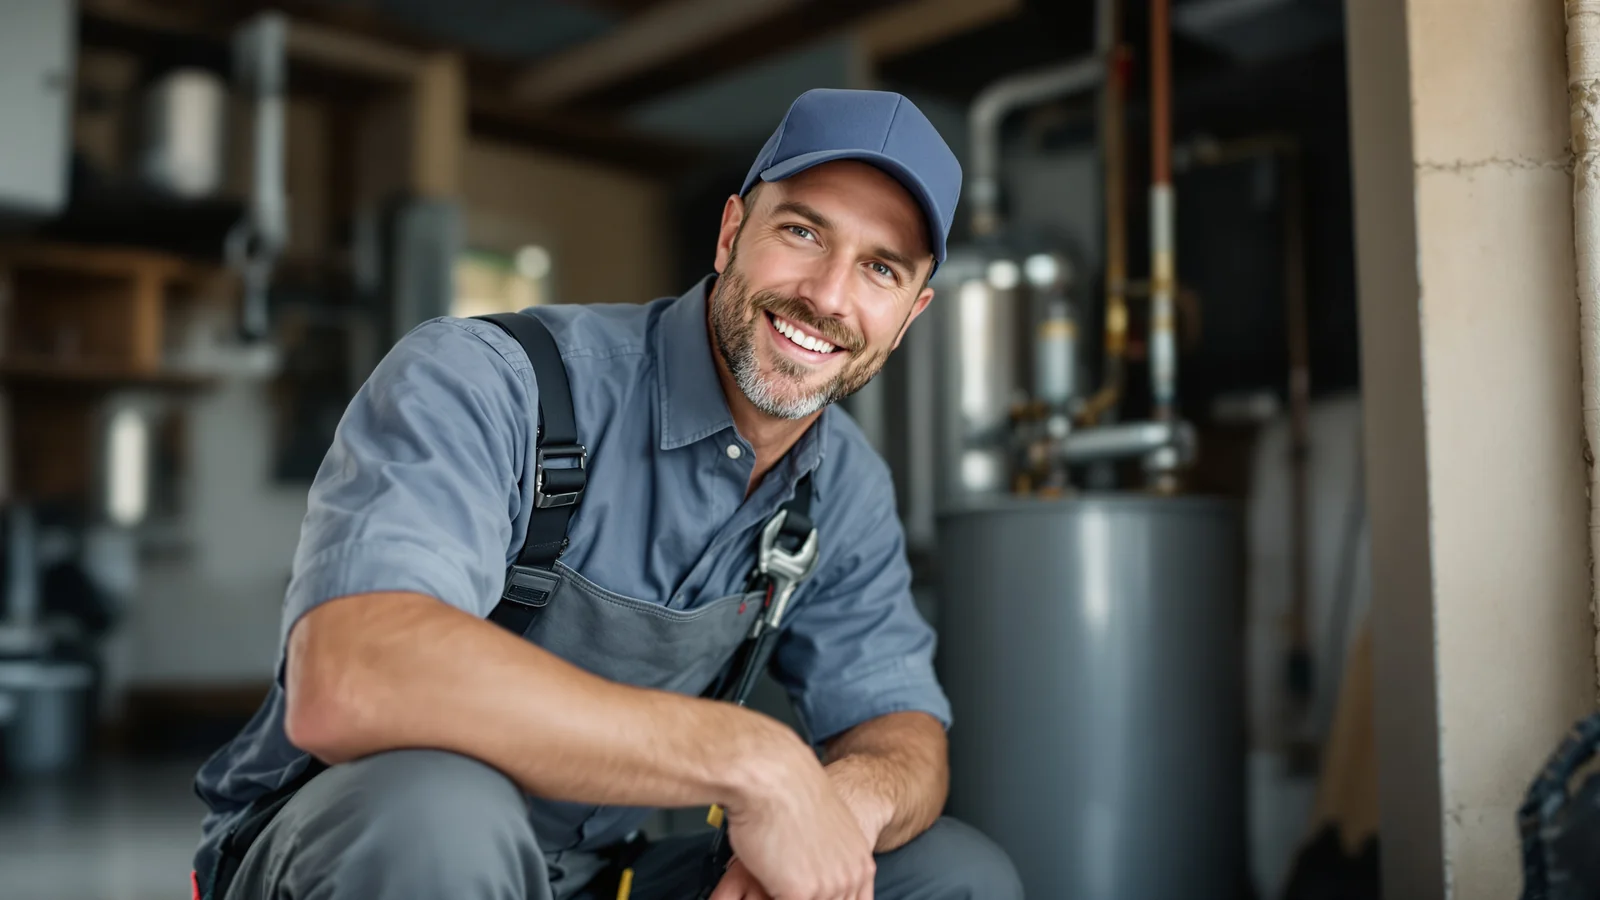
Plumber kneeling beside an open water heater in a Florida residential garage, tightening a fitting with a pipe wrench
Sovic, the Sova Insurance mascot, holding a phone
🎯 Free Quote
Tell us about your business
One agency for GL, workers comp, auto, bonds and more
Please enter a phone number or email
🔒 Data protected ✅ No spam 💬 Free consultation
500+
Florida businesses insured
20+
commercial carriers compared
5.0★
rating on Google
Same-day
certificates of insurance
One Agency, Whole Stack

Everything your business needs to keep working

Six coverage types, one renewal cycle, and a Florida agency that specializes in contractor and trade insurance — not a generalist shop bolting it on.

General Liability

Required before most GCs let you on site.

Workers Compensation

Florida generally requires this for construction businesses with one or more employees — we’ll confirm what applies to you.

Commercial Auto

Your truck is not covered by a personal policy.

Tools & Equipment

Replaces what gets stolen off the job.

Surety Bonds

Bid, performance and payment bonds.

Builder’s Risk

Covers the project while it’s going up.

Most contractors we meet have four policies from four agents, renewing on four different dates, and nobody who has seen the whole picture. We write all of it, renew it together, and answer the phone.
Certificates of Insurance

Certificates the same business day you ask

Need a COI for a job starting tomorrow? Send us the requirements and we’ll get it back the same business day. Additional insured endorsements included — no callback queue, no waiting on an underwriter.

Request a COI →
Contractor's gloved hands holding a phone at a job site to request a certificate of insurance
By Trade

Coverage built around how your trade actually works

Plumbing

Plumbers carry some of the highest liability exposure of any trade — a slab leak repair gone wrong, a water heater install that floods a unit below, or a sewer line job on a commercial property can turn into a claim fast. Most GCs and property managers won’t let a plumbing sub on site without a certificate naming them as additional insured.
Real risk: a botched water heater connection floods a condo unit two floors down. GL covers the property damage claim — without it, that’s coming out of your pocket.
Plumber installing copper pipework under a kitchen sink in a Florida home
HVAC technician servicing an outdoor air conditioning condenser unit beside a Florida home

HVAC

HVAC techs work with refrigerant, electrical connections and rooftop units — installs and service calls where a mistake can mean fire damage, electrical faults or a system failure in a Florida summer. Commercial HVAC subs almost always need to show proof of coverage before starting a job.

Real risk: a condenser install shorts out and starts an electrical fire. GL and the right equipment coverage are what stand between you and a five-figure claim.

Electrical

Electrical work carries obvious risk — panel work, rewiring, and commercial installs where a mistake isn’t just costly, it’s dangerous. Florida licensing and most commercial contracts require proof of GL and workers comp before an electrician steps on a job site.
Real risk: a wiring error causes a fire after the job is done. Completed-operations coverage under your GL policy is what responds months later, not just during the job itself.
Electrician wearing insulated safety gloves working inside a residential electrical panel
Roofer wearing a safety harness laying shingles on a Florida residential roof

Roofing

Roofing has the highest injury risk of any trade on this page, and carriers price it accordingly — workers comp is not optional once you have a crew. Most GL policies for roofing also come with stricter safety and documentation requirements than other trades.

Real risk: a crew member falls during a tear-off. Workers comp covers the medical costs and lost wages — and in Florida, going without it as a construction employer carries real legal exposure.

Landscaping

Landscaping crews operate heavy equipment around other people’s property every day — mowers, trimmers, irrigation work near pools, patios and driveways. Commercial property managers routinely require a certificate before a crew is allowed on a recurring contract.
Real risk: a thrown rock from a commercial mower cracks a parked car’s windshield in a client’s lot. GL covers the claim without it coming out of the contract.
Landscaper operating a commercial mower on a Florida residential lawn with palm trees
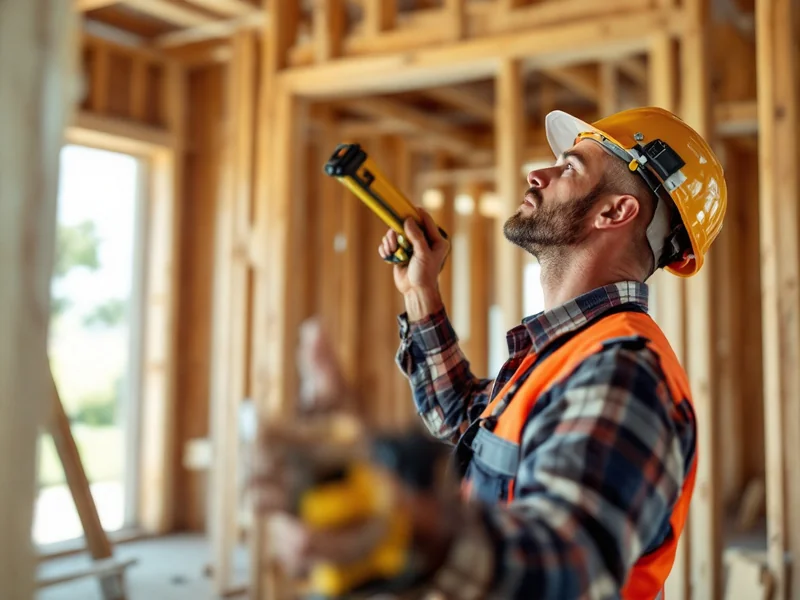
General contractor reviewing framing work inside a Florida house under construction

General Contractor

As a GC, you’re carrying liability for your own crew and coordinating certificates from every sub on the job. Builder’s risk covers the project itself while it’s under construction — something a standard GL policy doesn’t touch.

Real risk: a fire damages a project mid-build. Builder’s risk covers the structure and materials — without it, that loss falls on the GC.
Commercial Auto

Your truck is not covered by your personal auto policy

If your van is registered to the business, carries tools, or has your name on the side, a personal policy likely won’t respond after a claim. We write commercial auto for single trucks and small fleets.

Get a Truck Quote →
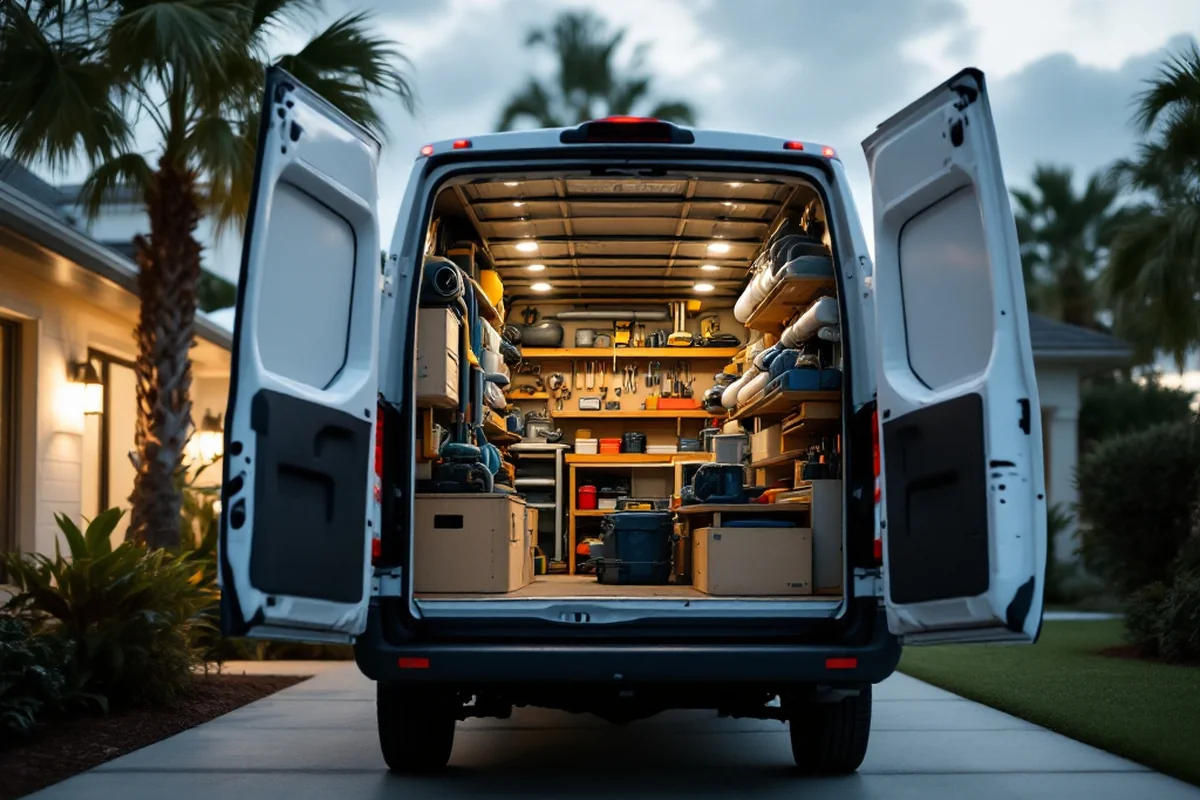
Contractor work van with rear doors open showing organized tool and pipe storage in a Florida driveway
Who We Work With

Built for how small contractors actually operate

★★★★★
5.0
Rated on Google by Florida clients
Read our reviews on Google →
How It Works

Three simple steps

Tell us about your business, we compare carriers, you get quotes and a certificate.

1

Tell us about your business

Trade, crew size, and the coverage you need — takes about a minute.

2

We compare carriers

We check GL, workers comp, auto and bond markets for your trade and quote what actually fits.

3

Quotes and a certificate

Review your options, bind what works, and get your certificate of insurance.

Carriers We Write With

Commercial markets, not a single carrier

We compare across 20+ commercial carriers rather than selling one.
…and biBerk, Hiscox, Pie and more — 20+ commercial carriers in all

FAQ

Common questions

How much does contractor insurance cost in Florida?+
It depends on your trade, payroll, revenue and claims history — there’s no single number that applies across the board. We’ll put together a real quote based on your business.
Do I need workers comp for a one-person business?+
Florida generally requires workers comp for construction businesses with one or more employees, and the rules differ by trade and employee count. We’ll confirm exactly what applies to your business.
How fast can I get a certificate?+
Same business day for most requests, including additional insured endorsements. Send us the job requirements and we’ll get it back to you fast.
Is commercial auto really necessary for one truck?+
If the truck is registered to the business, carries tools, or has your business name on it, a personal auto policy likely won’t respond to a claim — even with just one vehicle.
What if I already have coverage elsewhere?+
We can review what you have and compare it against other carriers — no obligation to switch. Many contractors come to us specifically to consolidate four separate policies into one.
Do you write bonds?+
Yes — bid, performance and payment bonds alongside your other coverage.

Ready to stop juggling four policies?

Free quote, no obligation — tell us about your business and we’ll take it from there.

Some of the Insurance Companies We Represent

GEICO Progressive Kemper Bristol West Root Insurance Orion180 Assurity ManhattanLife GEICO Progressive Kemper Bristol West Root Insurance Orion180 Assurity ManhattanLife